All Categories
Featured
SOCAL Green Reporting for Commercial Portfolios
Table of Contents
According to the IFRS Foundation's June 2025 jurisdictional profile, Stage I obligatory reporting started for specific listed companies from yearly periods starting on or after 1 July 2025, Stage II starts on or after 1 July 2026 for another accomplice of listed companies, and Stage III begins on or after 1 July 2027 for all staying noted companies and SECP-licensed non-listed public-interest business.
Commercial Landscaping AnaheimThey are live compliance turning points. A 2nd ISSB-related advancement is similarly essential: the requirements are currently being tuned for implementation, not merely promoted. In December 2025, the ISSB released targeted modifications to the greenhouse gas emissions disclosure requirements in IFRS S2 in reaction to application challenges determined as business started applying the requirement.
Business ought to anticipate more examination on how emissions are measured, borders are defined, and data is controlled. A typical mistake in boardrooms is to read the EU's 2025 Omnibus plan as a retreat from sustainability reporting.
It likewise estimated that proposed CSRD scope modifications and future ESRS adjustments might decrease administrative expenses by about 4.4 billion each year. That is genuine simplification, however it is not deregulation in the broad sense many executives wished for. The tactical message is this: Europe is trying to decrease reporting concern, not get rid of reporting expectations.
Methods to Reach 2026 ESG Benchmarks
That indicates materiality judgments, consistency, and discussion quality will still matter in 2026 and beyond. Companies exposed to the EU needs to get ready for a reporting environment that is somewhat lighter administratively, however not looser in supervisory expectation. For smaller sized business and value-chain press reporters, the important EU advancement is the voluntary SME standard.
That is a signal worth reading thoroughly. Even where reporting is formally voluntary, value-chain pressure is making structured disclosure significantly inevitable. The next wave of ESG reporting will be formed as much by format as by material. EFRAG's VSME digital template and XBRL taxonomy are planned to allow digital sustainability reporting for non-listed SMEs, with updated products launched through late 2025 and February 2026.
That may sound technical, however business meaning is uncomplicated: regulators, loan providers, clients, and software vendors significantly desire sustainability information in machine-readable kind, not just polished PDF narrative. This matters well beyond SMEs. When reporting becomes digital, inconsistencies emerge quicker, benchmarking ends up being easier, and guarantee gets sharper. Companies that still handle ESG reporting in fragmented spreadsheets and manual narrative workflows will find 2026 to 2027 uneasy.
A major pattern for 2026 and 2027 is that sustainability guarantee is becoming institutionalised. The IAASB's ISSA 5000 sets a global baseline for sustainability assurance and is effective from 15 December 2026, with early adoption encouraged. In parallel, IESBA's sustainability ethics and self-reliance standards also end up being efficient in December 2026, apart from particular value-chain independence provisions that come later.
The ramification is considerable. Business need to stop treating assurance as an end-stage external review and start treating it as a style requirement. In useful terms, that implies stronger internal controls, clearer documents of methodologies, much better governance over price quotes and presumptions, and more disciplined usage of external experts. By 2027, weak evidence tracks and vague narrative claims will be even more exposed than they were in the first generation of ESG reporting.
Optimizing SOCAL Regional Centers for ESG
TNFD's 2025 Status Report identified more than 500 first- and second-generation nature-related reports and said 620 organisations from over 50 countries or areas had actually openly dedicated to begin TNFD-aligned reporting for fiscal years 2024, 2025, or 2026. TNFD is likewise continuing to deepen sector assistance, with draft innovation and interactions assistance open for assessment and last sector guidance expected by June 2026. For organizations, the crucial takeaway is not that every business needs a separate nature report tomorrow.
Sectors with supply-chain direct exposure, land-use intensity, water reliance, extractives, food systems, infrastructure, or pharmaceuticals need to presume that nature-related metrics and narrative will become more material in 2026 and 2027. GRI remains highly pertinent, particularly for stakeholder-oriented and impact-focused reporting. Its modified Environment Change and Energy Standards, GRI 102 and GRI 103, were published in June 2025 and take impact for reporting from January 2027.
That suggests business utilizing GRI, especially those with high-impact sectors or broad stakeholder expectations, ought to not assume their existing disclosures will stay sufficient. The broader lesson is that the market is separating into two linked but unique reporting questions: what matters to enterprise worth, and what matters to individuals and planet effects.
The rules use to large companies doing organization in the state, with thresholds depending on the statute. The practical consequence is that even where federal ESG politics remain contested, big business can not presume delay all over. They need a jurisdiction-by-jurisdiction preparedness strategy. For many multinationals, 2026 will be the year when state-level disclosure commitments, EU requirements, and ISSB-based investor expectations start clashing inside one reporting calendar.
Readying Commercial Facilities for 2026 ESG Benchmarks
Build one core reporting architecture anchored in ISSB principles, then map outside to ESRS, GRI, California, and sector-specific requirements. Treat assurance preparedness as a 2026 build concern, not a 2027 clean-up workout. Digitise sustainability information collection, controls, and tagging early, particularly where SME or value-chain data will be pulled upstream.
Translate regulative due dates into board-level choices now, due to the fact that reporting calendars for 2026 and 2027 are already being set by regulators, not by internal convenience. ESG reporting in 2026 and 2027 will be more assembled at the top, more demanding in execution, more auditable, and less forgiving of weak information.
Those that wait will find that the reporting challenge is no longer writing the story. It is developing the system behind it.
Last updated: April 8, 2026ESG data and sustainability metrics are shaping how enterprises run, report, and manage business sustainability. As disclosure requirements broaden across structures such as CSRD and IFRS S2, companies are under increasing pressure to produce dependable, audit-ready information across finance, operations, and supply chains. This guide brings together the key sustainability statistics for 2026, covering business adoption, reporting obstacles, carbon accounting, and the growing expectations from investors and regulators.
Future Evolution of CRE Landscaping Through ESG
76% of executives state sustainability is main to business strategyOnly 1 in 5 finance teams presently report on their company's ESG metrics47% of financiers cite ESG information coverage gaps as their biggest challenge41% report information quality concerns, and 40% emphasize disparities throughout vendors84% of S&P 500 business now identify environment change as a monetary danger, a considerable increase from 67% in 202196% of G250 business report on sustainability (unchanged given that 2022)85% of investors state greenwashing claims have become a more major issue than they were 5 years ago58% of investors are making regulation-aligned ESG information a priority57% of organizations state client and investor expectations are the main driver of ESG strategyScope 3 emissions represent as much as 7090% of overall corporate emissionsGlobal ESG properties under management are predicted to reach $40 trillion by 2030 Sustainability is now embedded in core company decision-making.

Latest Posts
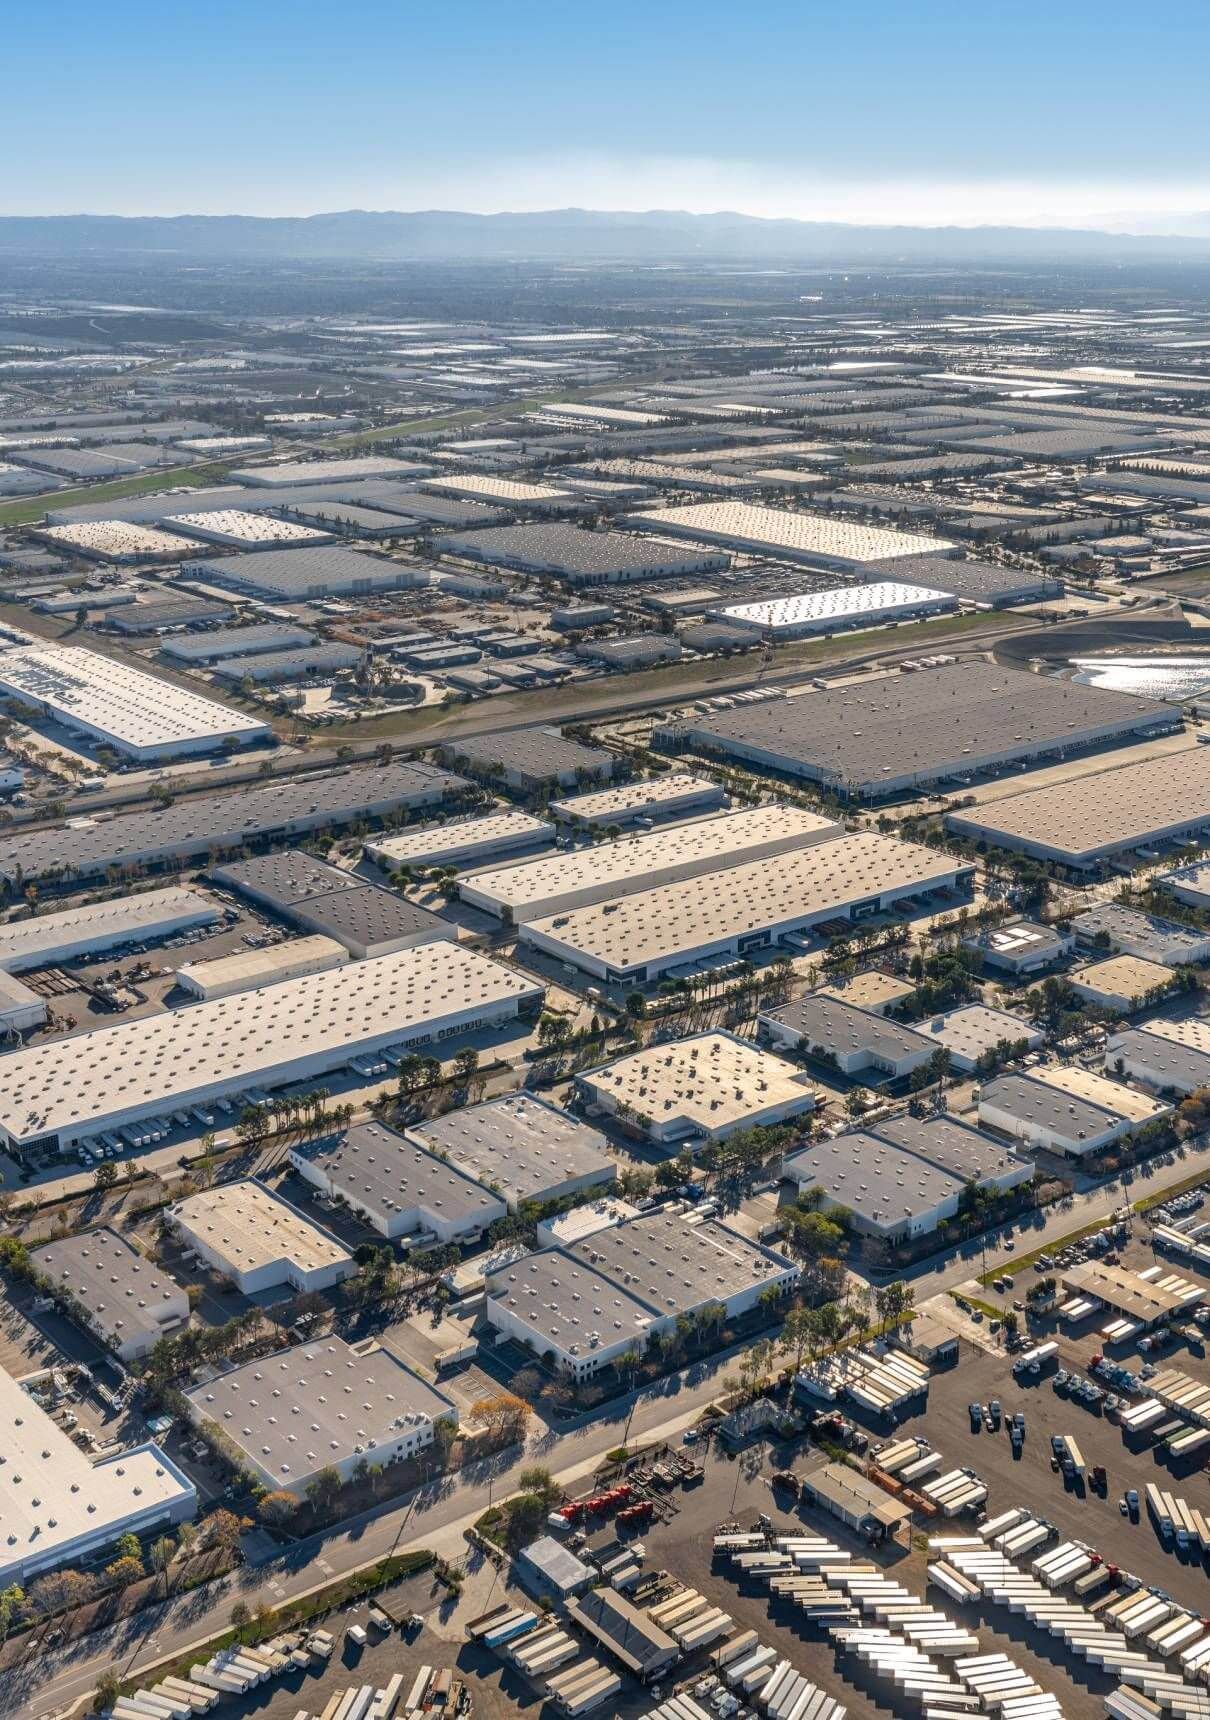
Future-Proofing SoCal Properties Via Sustainability Audits
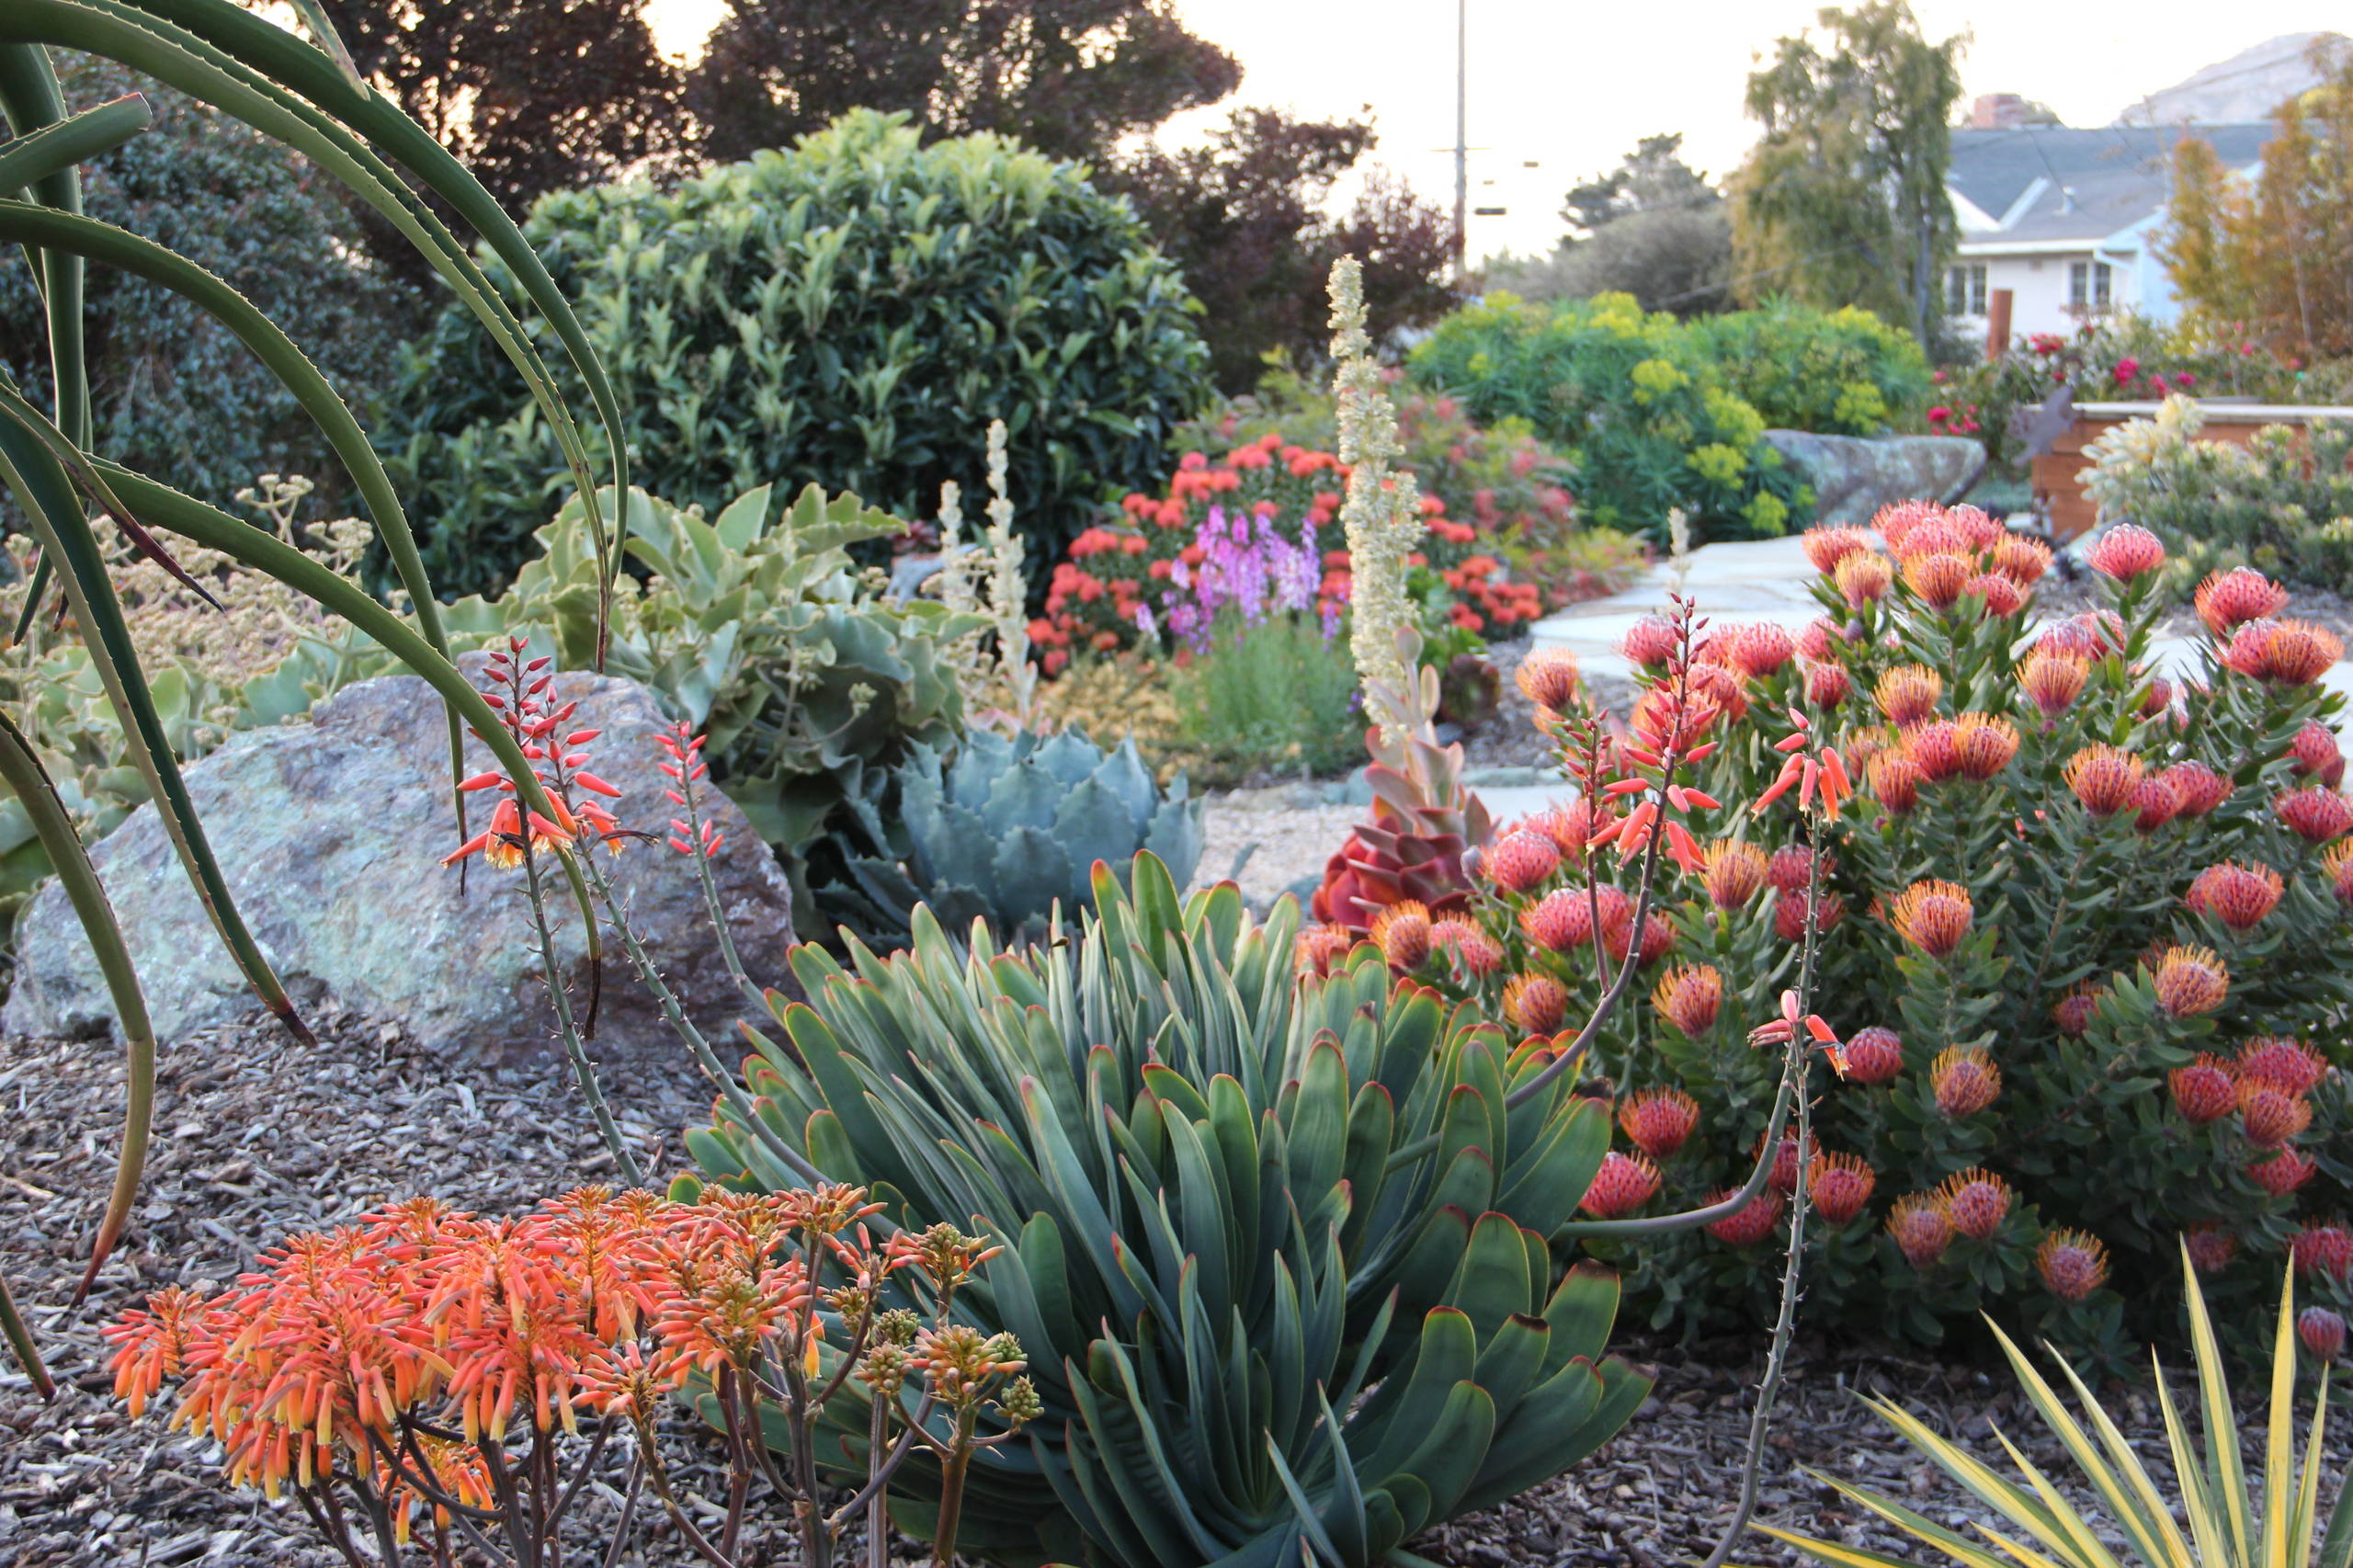
Key Benefits of Using California-Friendly Plant Varieties
Aligning Commercial Greenspace With 2026 ESG Standards